Cracks in the wall? How subsidence claims work
Not every crack is subsidence, and not every policy covers it. How to tell, what it costs you, and why you should call before you fill anything in.
 Gareth Pryce, insurance expert
· 1 min read
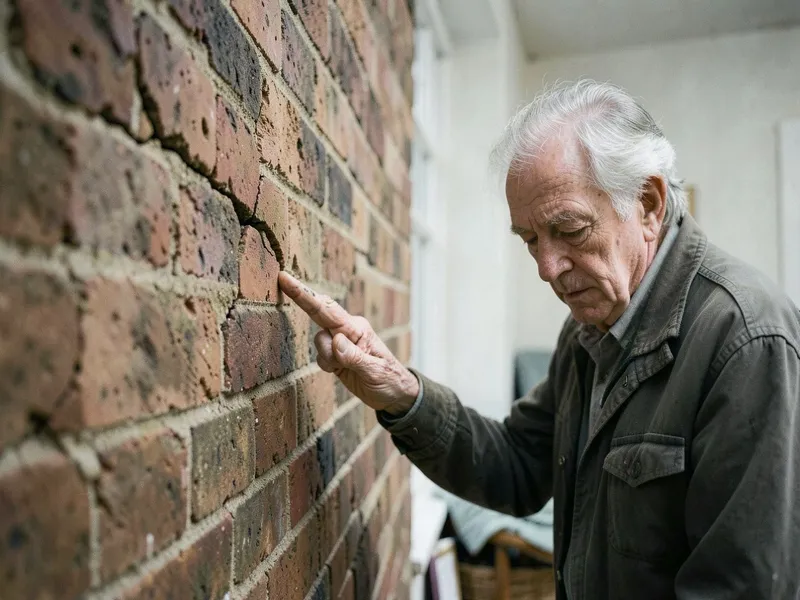
Subsidence is the ground under a house sinking or shifting, taking the foundations with it. It is rare, slow and expensive, and it is the claim people most often discover too late.
Is it subsidence?
Hairline cracks in new plaster are almost always shrinkage. Look instead for:
- cracks wider than 3 mm (a £1 coin’s edge fits in);
- cracks that are wider at the top than at the bottom, often running diagonally from a window or door;
- doors and windows that suddenly stick;
- cracks you can see inside and outside in the same place.
What a claim involves
Your insurer sends a loss adjuster, then usually monitors the crack for six to twelve months before deciding what caused it. Clay soil and trees are the usual causes. Repairs range from filling and redecorating to underpinning the foundations.
What it costs you
The subsidence excess is £1,000 on almost every policy, whatever excess you chose. Most policies in our comparison cover subsidence; two leave it out, and both say so on their page.
Before you buy
Tell the insurer if the house has had subsidence before, even if it was fixed. A policy taken out without saying so can be cancelled when you claim.